Roth IRA vs Traditional IRA: Which Is Better in 2026?
Roth vs Traditional IRA — the answer depends on your tax bracket today and in retirement. Here's the math, with real examples.
Written by

Sarah Chen
Senior Financial Editor - CPA, CFA
Sarah Chen is a Certified Public Accountant and Chartered Financial Analyst with 12+ years of experience in personal finance and tax planning. She previously worked as a senior analyst at a major US investment firm and now leads Qudexa's finance and tax content. Sarah reviews every calculator formula and finance guide on Qudexa for accuracy.
Reviewed by David Park (CFA, MBA)
Last reviewed: October 15, 2026
🤍 Found this helpful?
Give it a like — it helps others discover it
🌱 Roth vs Traditional IRA: The Complete 2026 Guide
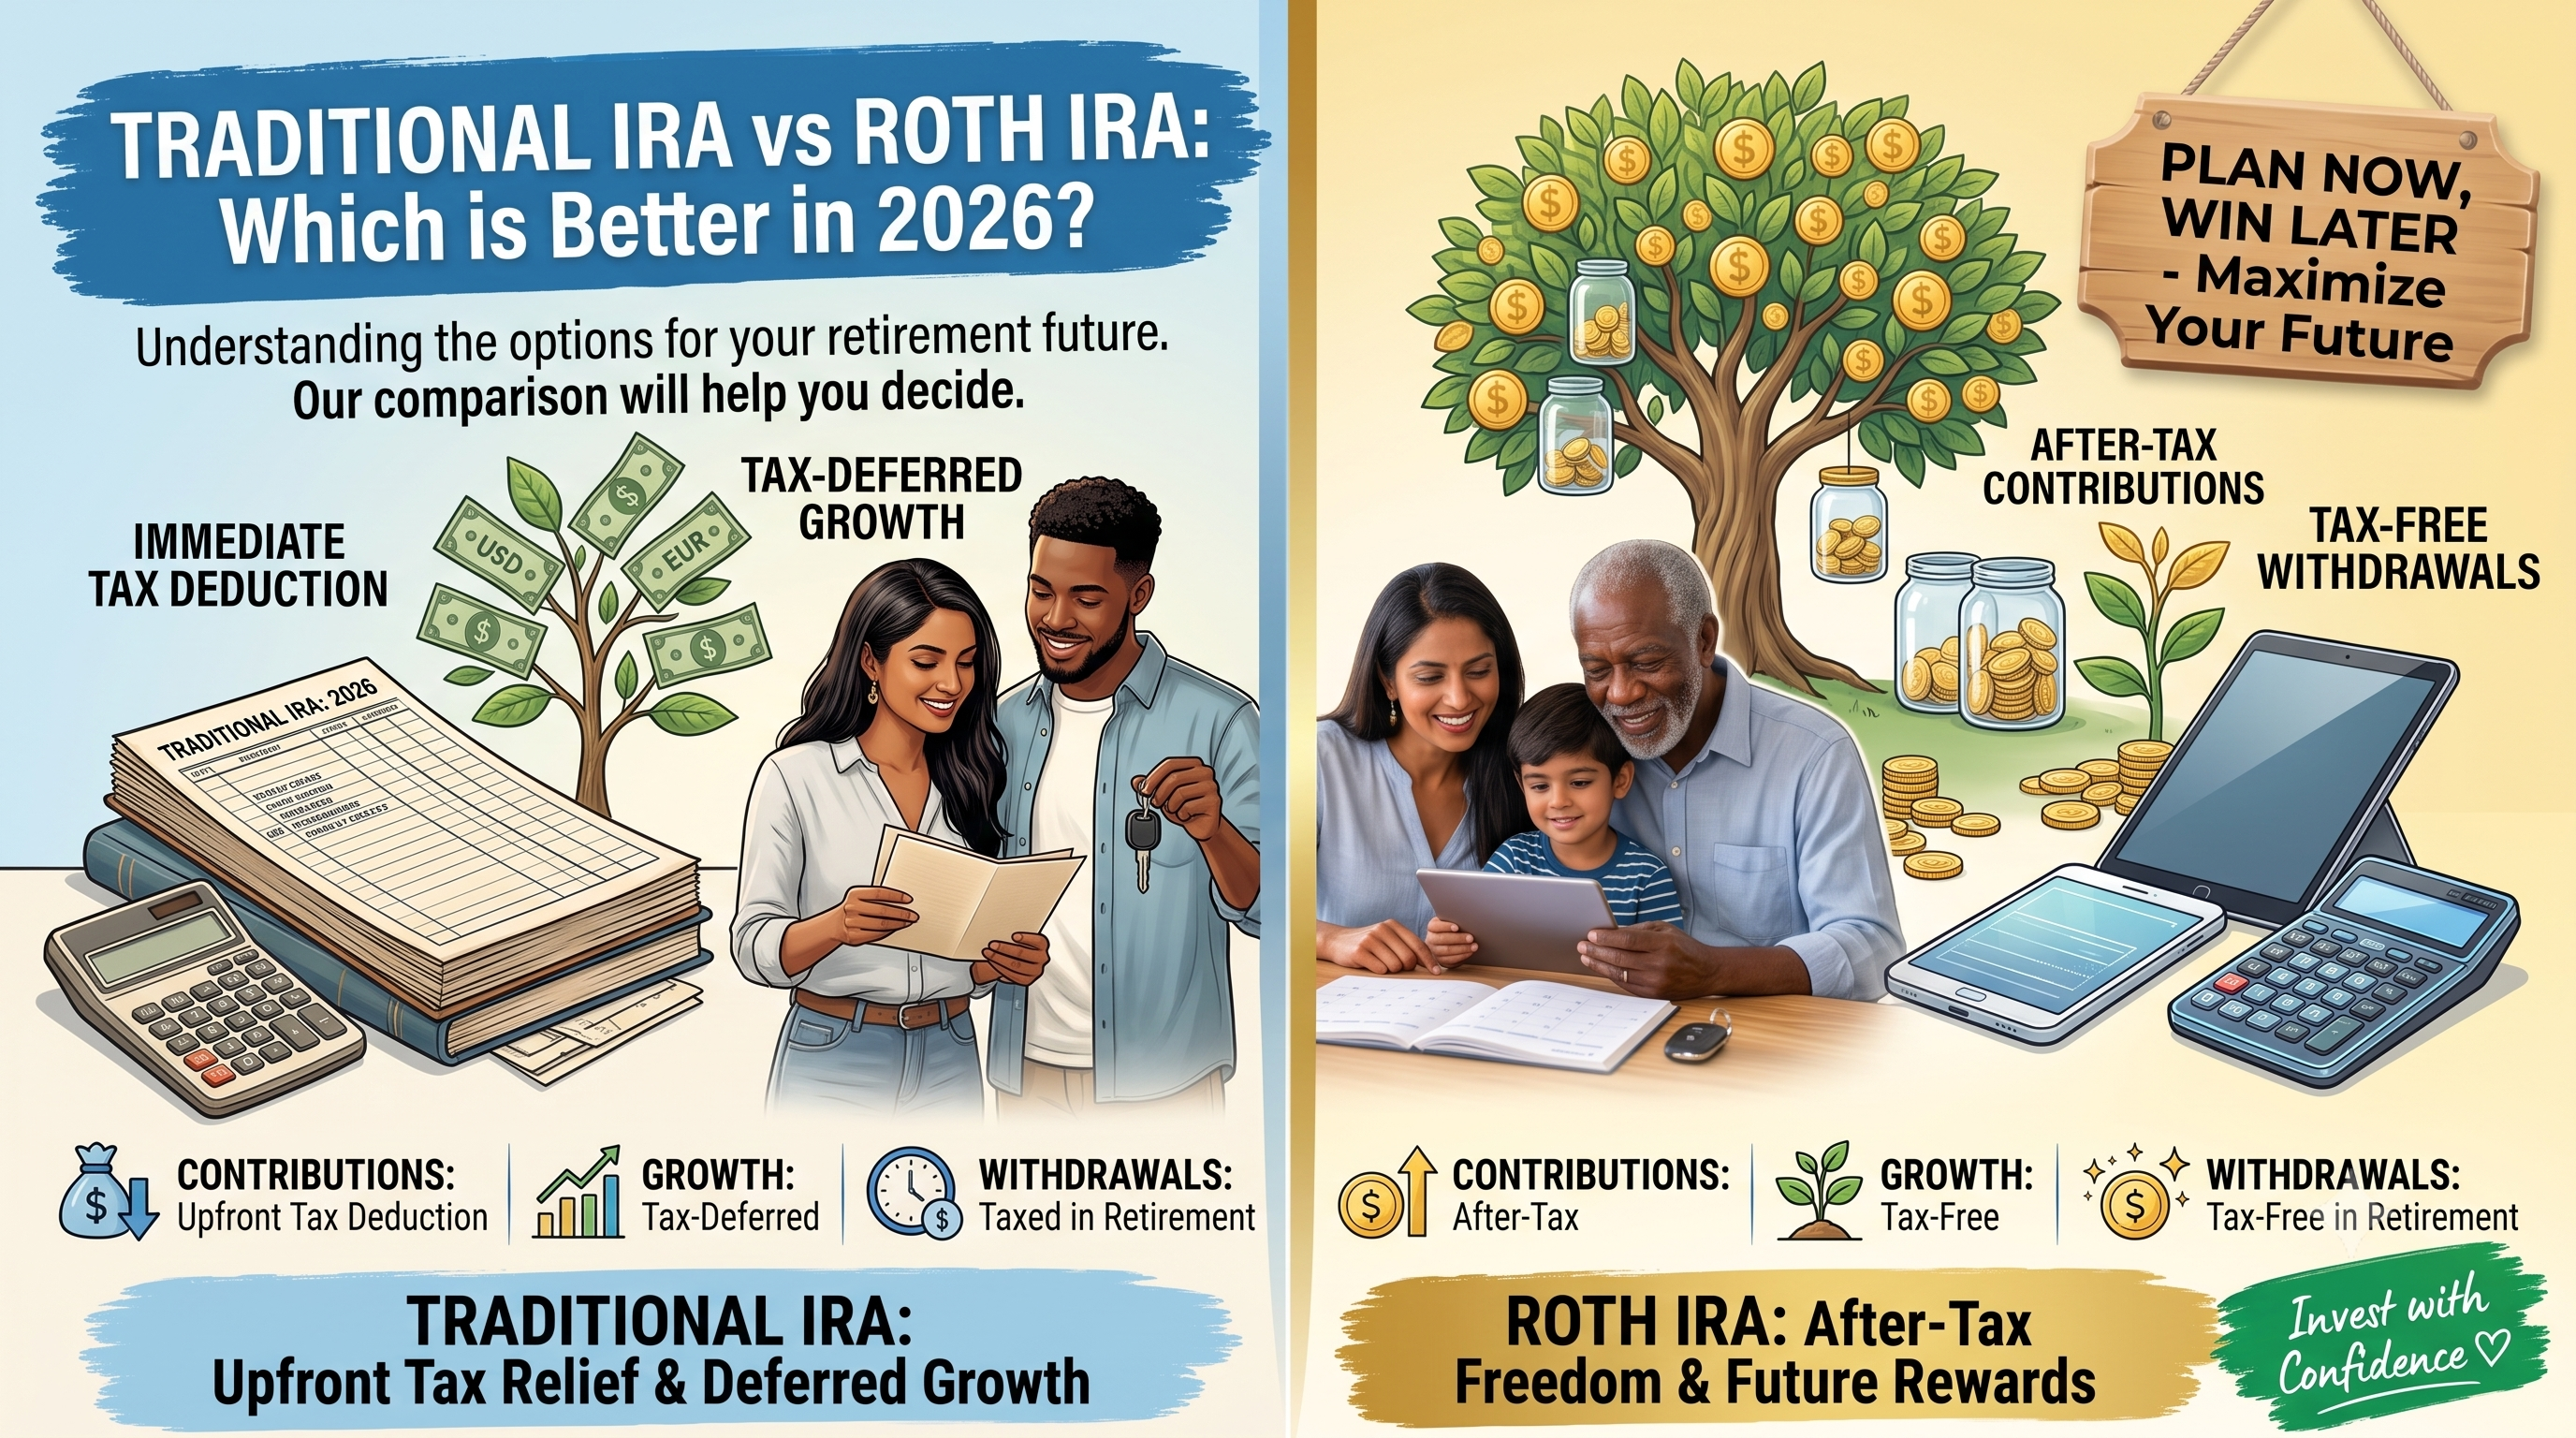
Both Roth and Traditional IRAs are incredible retirement accounts — but they work in opposite ways. Roth is taxed today, tax-free later. Traditional is tax-free today, taxed later. Which wins? Depends on your tax rate today vs. tomorrow.
Roth wins if you're early in your career, expect a higher tax bracket later, or want tax-free income in retirement. Traditional wins if you're in a high bracket now and expect lower income in retirement. See your projected balance with the Roth IRA Calculator.
⚖️ Side-by-Side Comparison
| Feature | Roth IRA | Traditional IRA |
|---|---|---|
| Contributions | After-tax | Pre-tax (maybe deductible) |
| Growth | Tax-free | Tax-deferred |
| Withdrawals | Tax-free (age 59½+) | Taxed as ordinary income |
| RMDs at 73 | None | Required |
| 2026 Limit (under 50) | $7,000 | $7,000 |
| Catch-up (50+) | $8,000 | $8,000 |
| Income limit | Yes (phase-outs) | No (if no employer plan) |
📊 2026 Contribution Limits & Income Phase-Outs
Single: $146K – $161K
Married: $230K – $240K
Above these limits: no direct Roth contributions (use backdoor)
No employer plan: fully deductible
With plan, single: $79K – $89K phase-out
With plan, married: $126K – $146K phase-out
🧮 Real Example: $7,000/year, 30 years, 8% return
| Metric | Roth IRA | Traditional IRA |
| Annual contribution | $7,000 | $7,000 |
| Tax savings today (24% bracket) | $0 | +$1,680 |
| Balance at 65 | $762,000 | $762,000 |
| Tax on withdrawal (22%) | $0 | −$167,640 |
| Take-home in retirement | $762,000 | $594,360 |
In this scenario, the Roth wins by $167,640 — because the person was in a lower bracket at retirement than during their working years. Run your own numbers with the Roth IRA Calculator.
Many financial advisors recommend a mix of Roth and Traditional accounts for tax diversification. When you retire, you can pull from Roth in high-income years and Traditional in low-income years to minimize lifetime taxes.
❓ FAQ
Can I contribute to both a Roth and Traditional IRA?
Yes, but the $7,000 limit is combined across both. You can't put $7,000 in each. Split it however you like.
What's a backdoor Roth IRA?
If your income is above the Roth limit, you can contribute to a Traditional IRA (non-deductible) and immediately convert it to Roth. Legal, common, and used by millions of high earners.
Can I withdraw Roth IRA contributions early?
Yes — contributions (not earnings) can be withdrawn tax-free and penalty-free at any time. This makes Roth IRAs double as emergency funds for many people.
Which is better for young people?
Usually Roth, because decades of tax-free growth is incredibly powerful, and your income (and tax bracket) will likely be higher later. A 25-year-old earning $50K is often better served by a Roth.
See Your Roth IRA Growth
Free calculator shows tax-free balance, contributions, and monthly retirement income.
🧮 Try the Roth IRA Calculator →Tags
🤍 Found this helpful?
Give it a like — it helps others discover it
Explore Free Calculators
Use our free online tools to calculate real numbers instantly.